Cost of Goods Sold (COGS)
COGS measures all direct costs a business incurs to produce or acquire the goods it sells, giving you control over margins, inventory, and pricing.
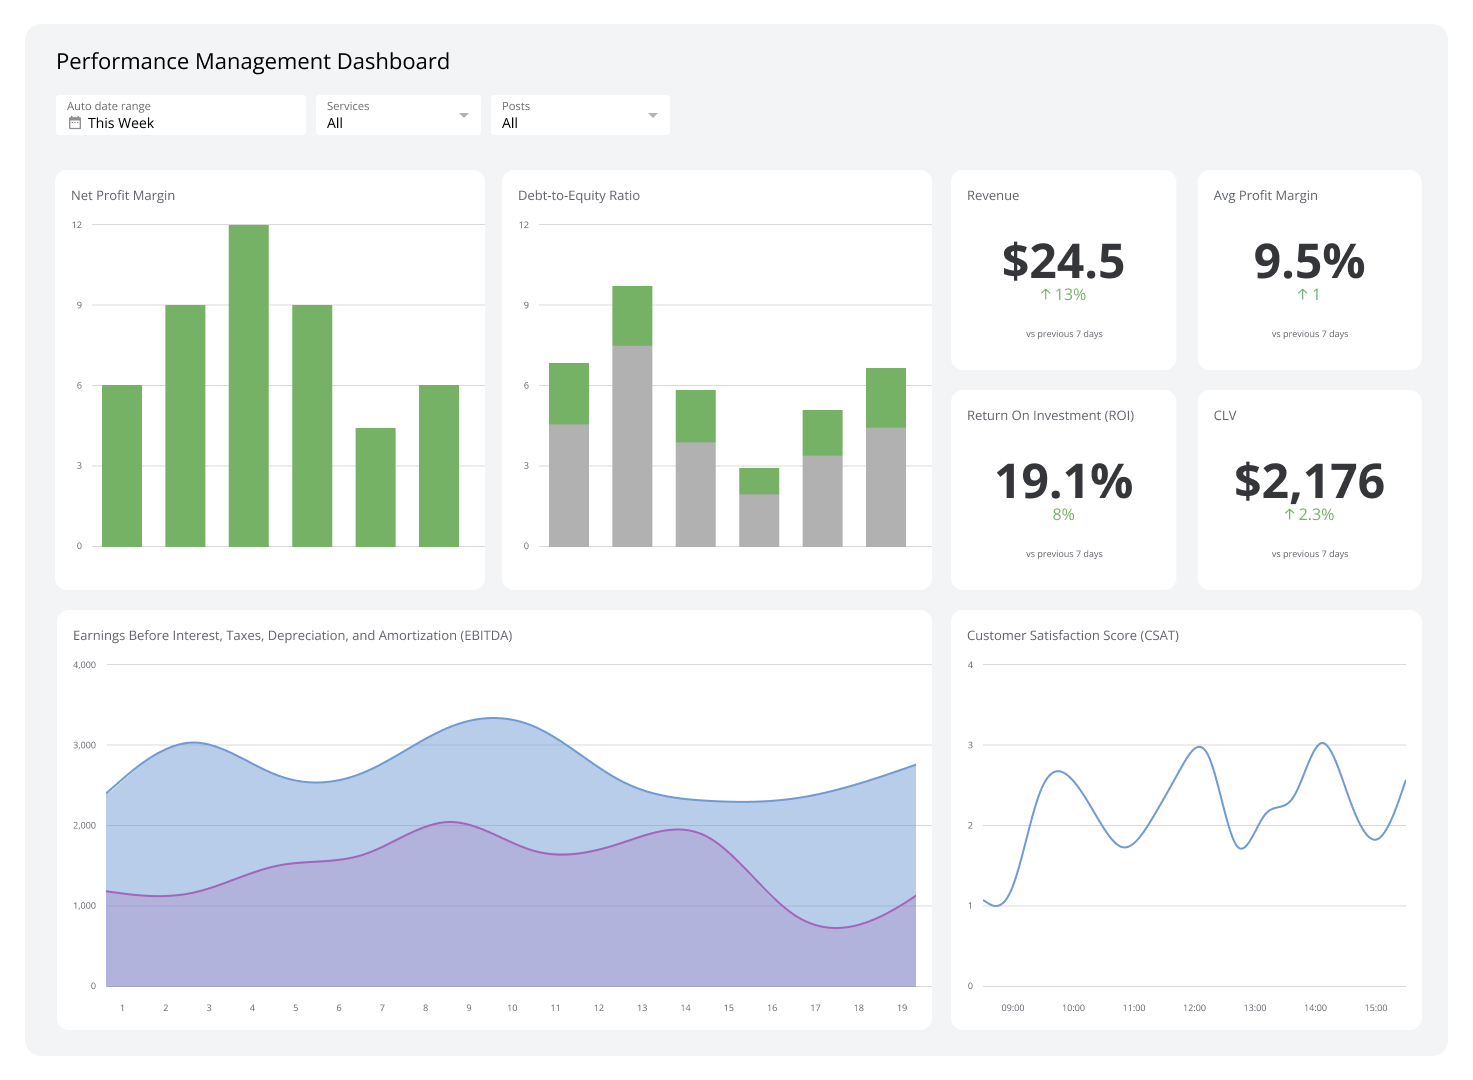
Cost of Goods Sold breakdown
Cost of Goods Sold (COGS) measures all direct costs a business incurs to produce or acquire the goods it sells during a specific period.
Understanding Cost of Goods Sold helps you see exactly where money goes before a sale becomes profit. Track it accurately and you gain control over margins, inventory, and pricing decisions.
What is Cost of Goods Sold (COGS)?
Cost of Goods Sold (COGS) is the total of all direct costs tied to producing or acquiring the goods a business sells. It excludes indirect expenses such as marketing, rent, and utilities.
Direct costs typically included in COGS are:
- Raw materials used in production
- New goods purchased for resale (for retailers)
- Packaging costs tied to the product
- Direct labour for employees involved in production
- Storage costs for inventory
- Depreciation on production equipment or assets
The exact costs vary by business type. Some companies also include sales commissions when those costs are directly tied to completing a sale. As production volume rises, COGS rises too, even if the selling price stays flat.
How to calculate Cost of Goods Sold
Cost of Goods Sold appears on the income statement, below the revenue line. To determine your gross profit, subtract COGS from total revenue. A higher COGS means lower gross profit, which flows through to a smaller net profit.
The standard formula is:
COGS = (Starting Inventory + Purchases Made During the Period) - Ending Inventory
The ending inventory from one year becomes the starting inventory for the next. Always use last year's closing inventory figure as this year's opening value.
To calculate COGS accurately:
- Identify all production costs incurred during the period
- Separate direct from indirect costs (only direct costs go into COGS)
- Total the direct costs, including materials, labour, and freight
- Add purchases made to replenish inventory or raw materials
- Calculate ending inventory value using your chosen accounting method
This key performance indicator gives you a clear view of how much it costs to generate revenue, and where you might reduce those costs.
COGS examples
Once you have accurate figures for direct costs and inventory, the calculation is straightforward.
A note on labour: only include payroll for employees directly involved in production. A manufacturing plant would not add office staff salaries to its COGS calculation.
If a customer returns goods, add the value of those returns to ending inventory. The formula becomes:
COGS = (Starting Inventory + Purchases Made) - (Ending Inventory + Returned Goods)
Example with returned goods:
| Item | Amount |
|---|---|
| Starting inventory | $120,300 |
| Purchases made | $100,000 |
| Subtotal | $220,300 |
| Ending inventory | $61,000 |
| Returned goods | $2,000 |
| Ending inventory + returns | $63,000 |
| COGS | $157,300 |
Example using the basic formula:
| Item | Amount |
|---|---|
| Starting inventory | $20,000 |
| Purchases made | $12,500 |
| Subtotal | $32,500 |
| Ending inventory | $2,500 |
| COGS | $30,000 |
When goods are transported to your location, freight is a direct cost. Include it like this:
COGS = (Starting Inventory + Purchases Made + Freight) - Ending Inventory
Or, with returned goods:
COGS = (Starting Inventory + Purchases Made + Freight) - (Ending Inventory + Returned Goods)
Inventory valuation methods for COGS
The ending inventory value you use affects your COGS result. Three accounting methods are commonly used, and each produces a different outcome.
Weighted average method
The weighted average method calculates a single average cost per unit across all inventory purchased during the period. It does not prioritize when goods were bought.
For example, a company makes these purchases in one year:
- 500 units at $10
- 600 units at $8
- 700 units at $6
Total inventory value: (500 × $10) + (600 × $8) + (700 × $6) = $14,000
Total units: 500 + 600 + 700 = 1,800
Average cost per unit: $14,000 / 1,800 = $7.78
If 1,500 units are sold, COGS = 1,500 × $7.78 = $11,670
Ending inventory (300 units) = 300 × $7.78 = $2,334
First-In, First-Out (FIFO) method
The First-In, First-Out (FIFO) method assumes that goods produced or purchased first are sold first. Because older, typically lower-cost inventory is sold first, COGS tends to be lower under FIFO. Ending inventory carries a higher cost valuation, which can increase reported profit.
Last-In, First-Out (LIFO) method
The Last-In, First-Out (LIFO) method is the inverse of FIFO. The most recently produced or purchased goods are sold first. Because newer inventory often costs more, COGS is higher under LIFO, which reduces reported gross profit. This method is not permitted under IFRS but is used by some companies following US GAAP.
Create custom dashboards for you and your team.
Get started with KlipsBenefits of tracking Cost of Goods Sold
This financial metric does more than satisfy an accounting requirement. Tracked consistently, it drives better decisions across pricing, operations, and planning.
Cost clarity
COGS shows exactly which direct expenses go into producing your goods. That visibility helps you spot waste, renegotiate supplier terms, or identify where labour costs are higher than they should be.
Inventory control
Knowing how much inventory you move over a given period helps you stock the right quantities. It also reveals how much price flexibility you have without cutting into net income, and where overstocking is adding unnecessary storage costs.
Competitive benchmarking
COGS tends to be similar across companies in the same industry. Comparing your figures against competitors can reveal whether your sourcing, production methods, or supplier relationships are putting you at a cost disadvantage.
Tax compliance
Tax authorities require accurate COGS reporting to prevent under-reporting of profit. Maintaining precise records protects your business from penalties and audit risk.
Profitability improvement
A high COGS compresses margins. Understanding what drives that cost gives you options: adjust pricing, change suppliers, streamline production, or shift your product mix. Tracking COGS over time on a financial dashboard makes those trends visible before they become problems.
COGS is an operating expense, not an asset or liability. Reducing it directly improves gross profit without requiring a single additional sale.
Limitations of Cost of Goods Sold
COGS has one significant limitation: the figures used to calculate it can be manipulated. By adjusting inventory valuations or misclassifying indirect costs as direct ones, a company can inflate or deflate its reported profit.
This makes accurate, ethical accounting practices essential. Stakeholders rely on COGS figures to assess financial health, and distorted numbers undermine that trust.
Tracking Cost of Goods Sold over time
A single COGS figure is useful. A trend line is more useful. Tracking Cost of Goods Sold month over month, or quarter over quarter, on a dashboard helps you catch cost increases early, measure the impact of operational changes, and keep margins on target.
Klips connects to your accounting and inventory data sources so you can monitor COGS alongside gross profit, revenue, and net income in one view. When costs shift, you see it immediately rather than at month-end close.